There are a handful of household issues that look tiny on paper and somehow manage to carry the emotional weight of a holiday dinner gone sideways. Money is often like that. Not the dramatic kind tied to job loss or medical bills, but the ordinary, monthly kind that slips quietly into family routines and then hardens into expectation. I found that out over a cell phone bill, of all things, and what started as a practical deadline turned into one of the more revealing parenting moments I’ve had in years.
I’m in my early 50s, I live in a busy Midwestern city, and I’ve spent enough years running a home to know that the smallest systems are usually the ones holding everything together. In my kitchen, if I ignore a sticky drawer or a dull knife, eventually dinner tells on me. Family finances work the same way. By the time I finally drew a line and set a date, I thought I was solving a billing problem. What actually followed was part negotiation, part wake-up call, and, surprisingly, one of the clearest lessons my grown kids and I have had about respect, independence, and what support is supposed to look like.
1. Why I finally decided enough was enough
For years, I kept everybody on one phone plan because it was easier. The group rate was better, the autopay was already set up, and, like many parents, I had a lingering habit of smoothing over one more expense for my kids long after they stopped being kids. At first, that made sense. One child was in college, another was in that shaky early-career stretch where every paycheck already had three jobs lined up for it, and keeping them connected felt practical.
But practical has a shelf life. By this fall, I was covering lines for adults with jobs, apartments, streaming subscriptions, takeout habits, and opinions about espresso. The monthly bill had crept high enough that I started looking at it the way I look at a pantry full of duplicate jars—somebody has stopped paying attention. My total bill was just over $210 a month, and when I broke it down, each additional line worked out to roughly $35. That was not a catastrophic amount. That was exactly why it had gone unchallenged for too long.
2. The message I sent and the deadline I chose
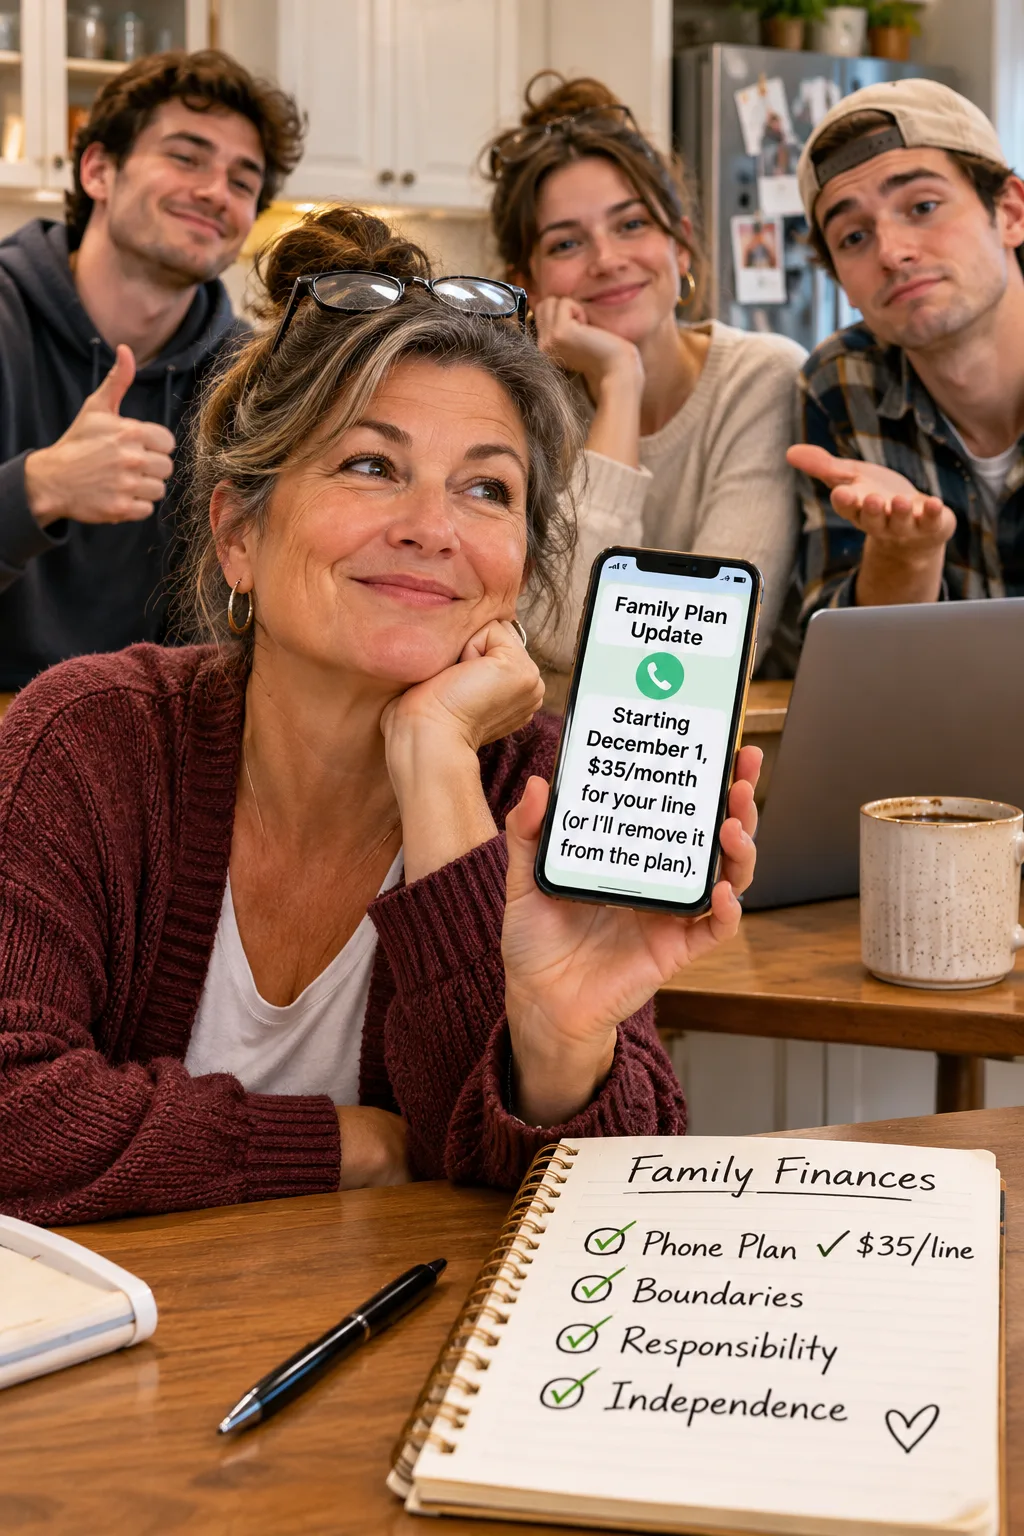
I did not make a speech. I sent a clear text. It said, in plain terms, that starting December 1, each adult child on my plan needed to pay $35 a month for their line or I would remove that line from the account. No all caps, no guilt, no passive-aggressive punctuation. Just the amount, the date, and the consequence.
I chose December 1 for a reason. It gave everyone several weeks of notice, enough time to ask questions, budget for it, or make other arrangements. I did not want this to be a surprise. In my experience, resentment grows fastest in vagueness. A specific date is like a timer in the kitchen: everyone knows when the bread comes out of the oven, and nobody gets to claim confusion when it’s done.
3. Why $35 mattered more than the dollar amount suggests
The interesting thing about $35 is that it sits in that uncomfortable middle zone. It is not so large that it would reasonably sink an employed adult, but it is not so tiny that it can be ignored forever without intention. For many people, $35 is two fast-casual lunches, one rideshare across town, a couple of coffees and a pastry, or one forgotten app renewal plus a convenience-store stop. In other words, it is exactly the kind of money that exposes priorities.
I didn’t pick the number to profit from my children. I picked it because it reflected the actual cost of carrying each line while still giving them a substantial discount compared with many individual plans. In my area, a single unlimited line can run $55 to $85 before taxes and fees, depending on the carrier. On my plan, they were still getting the cheaper option. I was simply no longer volunteering to subsidize it indefinitely.
4. The first reactions I got were not all the same
The responses came in waves. One child replied within 10 minutes with some version of, “That’s fair.” Another asked whether payment was due on the 1st or before the 1st. That was my organized one, the child who probably has color-coded folders somewhere. The third response took much longer and carried the familiar tone of someone hoping logistics might erase accountability. It was not an outright no. It was more like, “Can we talk about it?”
And that, frankly, was the real beginning. Family money conversations are rarely about the invoice in front of you. They are about history. Who has always been rescued. Who believes help equals love. Who hears a boundary and translates it as rejection. I had one child who took it as a normal adult expense, one who treated it as an administrative detail, and one who heard it emotionally first and financially second.
5. What the bill had really become inside our family
When I sat with it, I realized the phone plan had become a quiet symbol. It wasn’t just a utility. It was one of those invisible cords parents leave attached because no one has paused to cut and retie them. I know families that do this with car insurance, tollway transponders, warehouse club memberships, and the occasional baffling gym add-on. Nobody argues because the amount feels manageable. Then one day the parent notices they are still acting as the central billing department for people old enough to compare mortgage rates.
In my case, I wasn’t angry so much as tired of the assumption. There is a meaningful difference between helping and being automatically charged. I am generous by nature. I feed people. I send leftovers home in containers I never see again. I will absolutely pay for dinner and insist on dessert. But generosity lands differently when it is chosen fresh each time, not silently extracted every billing cycle.
6. The child who paid immediately
One of my children handled it exactly the way you hope an adult handles routine responsibility. They asked how I wanted the money sent, set up an automatic transfer, and paid the first month before I had even checked the account again. That response told me something important: clarity often invites maturity. When expectations are direct, capable adults usually rise to meet them.
The practical effect was small but satisfying. I no longer had to wonder whether I’d need to remind them. There was no monthly awkwardness, no chasing, no emotional residue. It was $35, transferred on schedule, and I could mentally close that drawer. If you are a parent reading this, that administrative peace is worth more than it sounds. So much family friction comes from repeat follow-up on things that should have been resolved once.
7. The child who negotiated like a young professional
Another child came back with a counterproposal, and I have to admit I respected the effort. They asked if they could pay on the 15th of each month instead of the 1st because that lined up better with their pay schedule and rent timing. That was not avoidance. That was budgeting. To me, that sounded like adulthood trying on its coat and seeing if the sleeves fit.
I said yes, with one condition: consistency. If the transfer came on the 15th every month, we were good. If it became irregular, the original deadline stood. We settled it in about five minutes. I appreciated that exchange more than I expected to. It reminded me that a boundary does not have to be rigid to be effective. Sometimes the best family rule is not “my way exactly,” but “show me you can manage your obligation responsibly.”
8. The child who pushed back the hardest
The toughest conversation was with the child who felt the change was abrupt, even though I had given advance notice. Their argument was layered. They said family plans save me money too. They said they were “barely using data.” They said they had a lot of expenses right now. All of that may have been true in pieces, but none of it changed the central fact: they were an adult using a service that cost money.
I stayed calm and repeated the same point in different words. I wasn’t punishing them. I wasn’t charging market rate. I was asking for a modest contribution for an ongoing monthly expense. I also pointed out, gently, that they had recently mentioned concert tickets that cost more than three months of phone service. I did not say that to score a point. I said it because priorities become visible when numbers are placed side by side.
9. What happened when December 1 actually arrived
Deadlines reveal character. By December 1, one child had paid ahead, one had made the agreed-upon arrangement for a midmonth transfer, and one had not paid. Not partially. Not “I forgot but just sent it.” Not “Can I send half?” It was simply unpaid, with a few last-minute texts that sounded more hopeful than concrete.
And this is where many parents wobble. We soften the consequence because enforcing it feels harsh. I understand that instinct. I had it too. But a deadline with no follow-through is just decoration. So I contacted the carrier, confirmed what was needed to remove a line, and told my child one final time that if payment was not received by the end of the day, I would proceed. The money did not arrive. I removed the line.
10. Taking someone off a family phone plan is less dramatic than it sounds
Administratively, the process was straightforward. Emotionally, it was not. My carrier’s customer service rep walked me through the options in about 20 minutes. In my case, the line could either be canceled or transferred out if my child wanted to start their own account and keep the same number. There may be transfer pins, account security steps, financing balances on devices, and timing rules depending on your provider, so it’s worth checking all of that in advance.
If you are in a similar situation, look at three details before making any move: whether the phone itself is paid off, whether the number can be ported without interruption, and whether there are any account-holder permissions required. A financed device can complicate things quickly. A phone with an unpaid balance may need to stay attached to the original account until the balance is cleared, and that is exactly the kind of fine print families ignore until they’re annoyed.
11. The fallout lasted about 72 hours
For roughly three days, I was apparently the villain in someone else’s coming-of-age story. I got cool replies. I got silence. I got one message implying I cared more about $35 than about family. That one stung, even though I knew it wasn’t true. Boundaries often get recast as cruelty by the person who benefited from the lack of them.
Then reality did what reality usually does. My child had to solve the problem. They researched plans, compared costs, and discovered that independent service was indeed more expensive than $35 on my plan. Within the week, the tone had changed from offended to practical. We moved from accusation back into information: What carrier has decent coverage? How much hotspot data do you actually need? Is prepaid a better fit for now?
12. What they learned when they had to price it themselves
I think this was the most valuable part of the whole episode. Until then, “the phone bill” had been abstract. Once my child had to shop for their own plan, the numbers became real. Entry-level prepaid options in our area started around $40 to $50 a month with taxes and limits. More robust plans climbed higher. Suddenly, my $35 contribution request looked less like parental opportunism and more like a bargain.
There’s a larger lesson there. Adult children do not always understand the value of what they’ve been receiving until they have to replicate it on their own. I don’t say that critically. Most of us learned that way. The first time you price out car tires, dental insurance, internet service, or a plumber who charges $125 just to ring the bell, your understanding of adulthood gets very specific very fast.
13. What I learned about fairness versus rescue
I had to examine my own habits too. Parents can become so accustomed to being the cushion that we stop noticing when support has drifted into overfunctioning. Fairness is not the same as sameness, and it is not the same as endless rescue. If one adult child is genuinely in crisis, I will help. If one is between jobs and communicating honestly, I will help. If one simply prefers not to add a routine bill to their budget, that is not crisis. That is preference.
As someone who cooks a lot, I think of it this way: feeding someone because they’re sick is care. Feeding someone every night because they can cook but don’t feel like planning is a different arrangement entirely. Neither is automatically wrong, but they are not the same thing, and confusion between them creates resentment faster than almost anything else.
14. The practical system we use now
After the dust settled, we created a simple system. The children who remained on the plan pay electronically on a set date each month. No cash, no “I’ll get you next time,” no vague promises attached to holiday visits. I keep a short note in my calendar with who has paid and when, the same way I track when I’ve refreshed my sourdough starter or replaced the water filter. Systems save relationships because they reduce interpretation.
I also made one rule for myself: I do not remind more than once. If payment is due on the 1st, I might send a quick note on the 28th or 29th as a courtesy. After that, adults manage adult tasks. That change alone lowered my irritation dramatically. Repeated reminders are expensive in a way spreadsheets do not show. They cost energy, patience, and goodwill.
15. If you’re thinking about doing the same thing, here’s what I’d suggest
Be specific. Put the amount in writing. Give a real date, ideally 30 days or more in advance. Know the actual cost per line before quoting a number. Check whether any phones are still financed. Decide in advance what consequence you are willing to follow through on, and only name the consequence if you truly mean it.
Also, don’t overexplain. You do not need a 900-word justification for expecting employed adults to contribute to a recurring bill. A calm sentence is often enough: “Beginning January 1, your share is $35 monthly. If that doesn’t work for you, I’m happy to help you transfer to your own plan.” Clear language is kinder than a long speech wrapped in apology.
16. This is what happened in the end
In the end, two of my adult children stayed on the family plan and now pay their share reliably. One came off the plan and opened their own account after discovering exactly what solo service costs. Nobody was permanently estranged. Thanksgiving still happened. People still ate too much. I still sent leftovers home. The family survived a boundary.
More than that, the air felt cleaner afterward. The resentment I had been carrying quietly was gone, and the kids had a sharper understanding of how family support works in this house. I am happy to help where help is needed. I am not interested in silently underwriting ordinary adult expenses forever just because I always have. For $35 a month, that turned out to be a pretty good lesson for all of us.